A new income category is drawing serious money - here's why (From Investors Alley)
Key Points
- Bank of America's Q3 revenue grew 3.2% but missed consensus estimates, largely due to an unexpected $1.2 billion money-laundering related legal charge.
- A post-earnings sell-off pushed shares below the lowest analyst price target, which analysts view as an overreaction creating a potential buying opportunity.
- Reliable dividends, aggressive share buybacks, improving credit trends, and expected NII growth support long-term upside despite near-term interest rate uncertainty.
- Special Report: SpaceX minted 4400 millionaires in a single day (From Behind the Markets)
Bank of America (NYSE: BAC) is a compelling play because of its scale, value, dividend, and sensitivity to interest rates.
While its Q3 results align with the broader financial sector, suggesting a cyclical investment peak in Q2, investors should not get this signal wrong. A peak is a peak, except when the economy is expanding versus contracting.
We’re looking at a multi-year, potentially longer economic expansion that has years to play out. Underpinned by AI, data center builds, onshoring supply chains, and favorable government support, the economic backdrop points to sustained growth at Bank of America and additional investment peaks to come.
The only question is timing, i.e., how quickly S&P 500 companies can reload their balance sheets in preparation for the next investment cycle. Between now and then, Bank of America pays a solid capital return, and its shares have returned to trend.
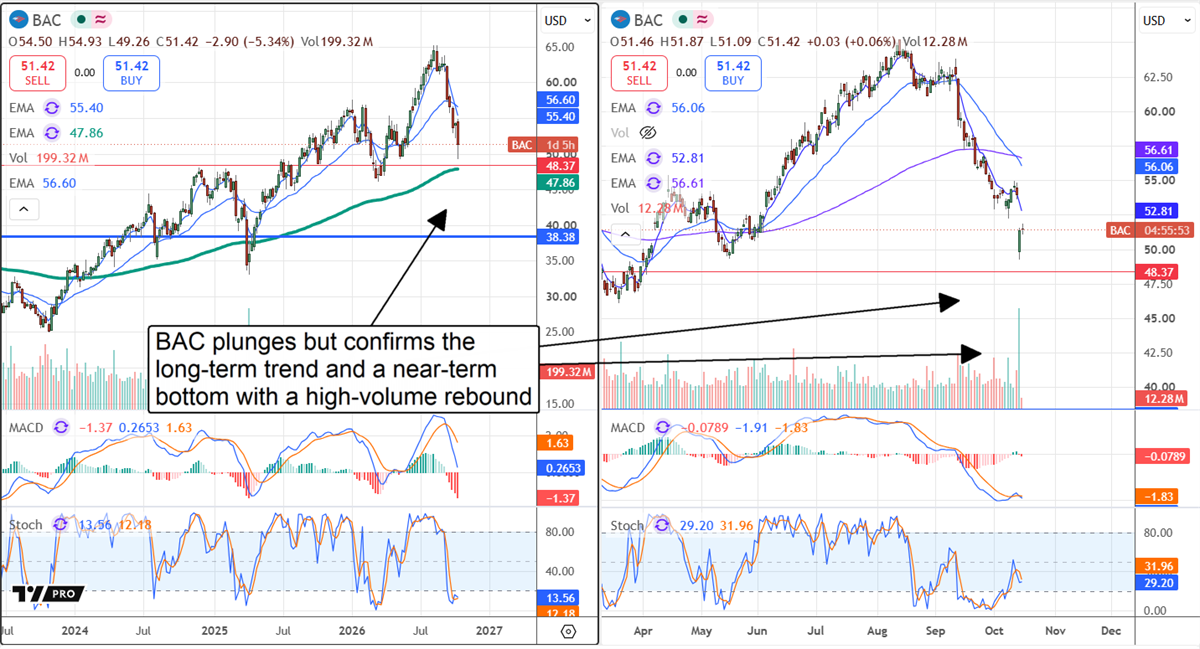
Technically, BAC’s market reverted to trend following its Q3 earnings release, indicating potential for a trend-following entry in mid-October. Support is marked by the converging long-term 150-week exponential moving average and 2022 highs. The EMA is noteworthy because it represents long-term buy-and-hold investors, such as the institutional group, which owns more than 70% of the stock and whose activity coincides with 2026’s stock price bottom.
Record Revenue Gold Silver Royalty Firm Still Trades Below 1 Dollar (Ad)
A small-cap gold and silver royalty company is generating record revenue from producing mines, yet shares still trade under 1 dollar.
It just signed the largest transaction in its history, a new gold streaming deal backed by a strategic relationship with a major mining investment firm.
A well-known sector financier has invested his own money and joins the CEO in an exclusive interview breaking down the full story.
Click here for instant access to the free report now
Q3 Earnings Reveal Strength Beneath the Headline Miss
Bank of America didn’t have a bad quarter, just a weaker one than expected, compounded by an unexpected legal charge. Authorities tagged BAC with a $1.2 billion charge tied to money-laundering controls and reporting, which impacted net earnings in the quarter. Revenue grew 3.2% to nearly $30 billion, missing consensus by more than $600 million, or 200 basis points. Strengths came from the Consumer and Global Wealth Management segments, which grew 4% and 13%, respectively, while weakness in Global Banking and Global Markets offset gains.
Key highlights include strength in NII, global banking fees, and balance sheet growth, which supported healthy cash flow despite the legal charges. Net income contracted significantly due to the impairment, but it is a one-off that the company can handle. Adjusted results were much better, nearly matching the analysts' forecasts despite the top-line miss, coming in at $1.08 versus the $1.10 consensus estimate. Looking ahead, the company reaffirmed its outlook for this year's NII growth, with growth expected to accelerate next year.
Balance sheet strength is evident in deposits and loan growth, which improved by 2% and 6%, respectively and in Tier 1 ratios, which remain well above target. The market worried that credit provisions were too low, but the initial sell-off was an overreaction. A closer look shows credit trends are improving, not worsening, supporting the lighter provision relative to loan growth.
BAC's Post-Earnings Sell-Off Creates a Buying Opportunity
Initial analyst responses to the report were mixed, with several price target reductions in the first few days. However, the reductions don’t alter the consensus view; instead, they align with it.
Also, Robert W. Baird issued a significant upgrade to Outperform from Neutral with a $62 price target, just shy of the consensus. This upgrade offers more than 20% upside from the critical support target and strengthens the consensus sentiment rating.
While the stock's price response was justifiable, it overreacted, falling below the lowest analyst price target and into a deep-value range. The key point for investors in late Q4 is that the plunge triggered a buying frenzy, leading to an immediate rebound backed by the strongest daily trading volume in 18 months. This signals the bottom of BAC's price correction and sets the stage for the next upswing, which may begin early next year. A sticky deposit base, NII growth, and interest-rate tailwinds support the business, and the stock trades at a significant discount to its peers.
Elon Musk’s 4th Wealth Window Set to Open by October 30 (Ad)
Jeff Brown, the analyst who flagged Bitcoin, Tesla, and Nvidia early, is tracking Elon Musk's next move. He points to a new AI project tied to Musk's Cybercab reveal.
Brown says Musk has opened major investment windows before, with PayPal, Tesla, and SpaceX marking milestones in tech history. He believes a fourth may open by October 30.
See Jeff Brown's full analysis on Musk's new AI project
Bank of America's Dividend and Buybacks Support Long-Term Upside
Bank of America’s dividend is reliable. Yielding about 2.5% as of mid-October, its buybacks are the question mark. The market gets it wrong, however, to think the $1.2 billion charge is sufficient to undermine the outlook; worse, to think a structural defect has emerged.
Buybacks are likely to continue at an aggressive pace. Share count fell more than 5.3% over the trailing 12 months, while the book value improved, giving shareholders leverage for the upswing.
The risk is that Bank of America's guidance prices in several more FOMC interest rate hikes. If the committee does increase rates, it will increase pressure on consumers—and if it doesn't, it will undermine the NII and buyback outlook.
Recommended Stories
- AST SpaceMobile Is Down 67%—Could SpaceX's Mobile Push Deepen the Selloff?
- Financial legend: “This is bad, really bad...” (From Weiss Ratings)
- GlobalFoundries' $21 Billion Deal Could Change the Economics of Chipmaking
- Inside a Former Merrill Lynch Advisor's Income Playbook (From Base Camp Trading)
- Fundamental and Technicals Signals Align for Costco: Is the Stock Finally Breaking Out?
- Palantir's Potential Next Catalyst After Retail Profit-Taking
- Morgan Stanley Beats on Earnings, But Shares Fall on Trading Mix
Stay Ahead of the Market
The best investment opportunities don't wait. Get our research and stock ideas delivered straight to your smartphone—so you never miss a market-moving opportunity. Our text alerts ensure you see timely stock ideas and professional research reports instantly, whether you're in a meeting, commuting, or away from your desk.


