A US Gold Explorer Approaches a Key Drilling Milestone (From Wall Street Logic)
Key Points
- Dave & Buster's stock hit a record low after weak Q2 results, but heavy volume and panic-selling suggest capitulation rather than a fresh downtrend.
- The company's Back-to-Basics strategy is generating positive free cash flow and outperforming remodeled stores, even as high debt and negative comp sales weigh on results.
- Nine analysts rate the stock a consensus Hold with price targets implying deep value, while high short interest and improving trends could eventually spark a rebound.
- Special Report: The REAL Reason Trump is Invading Iran (From Banyan Hill Publishing)
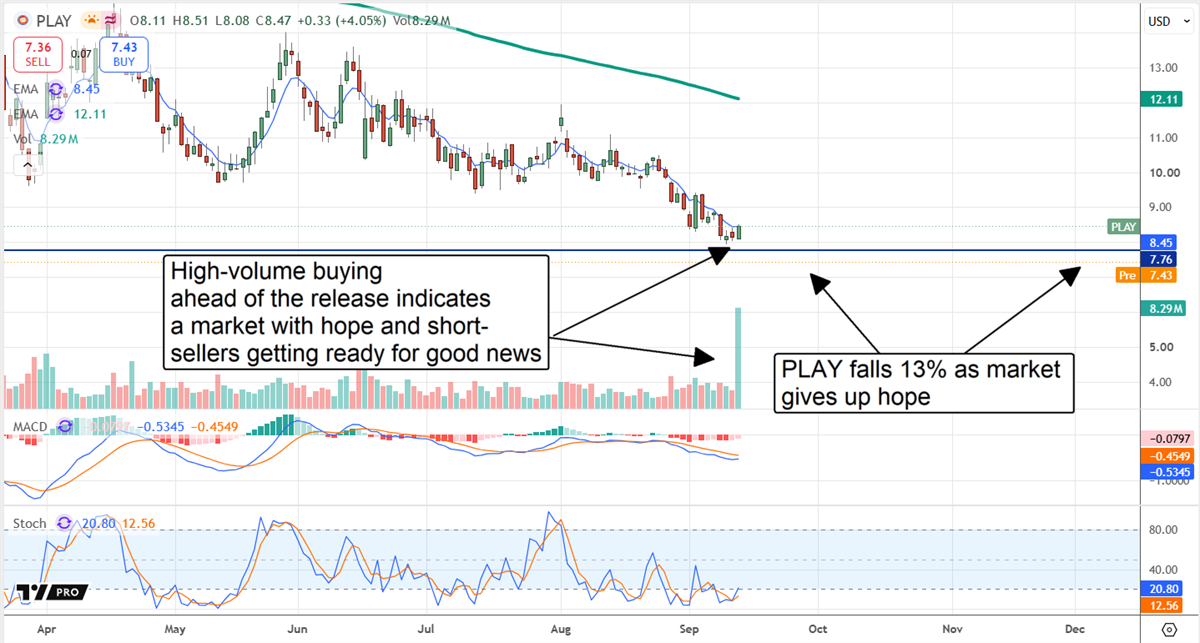
Dave & Buster’s (NASDAQ: PLAY) has its share of headwinds, but not to the degree its stock price action suggests. The mid-September plunge, triggered by weaker-than-expected Q2 results, pushed the stock to a record low, well below existing support and on track for what could be a monumental slide.
But the panic-selling and heavy volume behind the move have the hallmarks of market capitulation—the point at which investors give up hope and sell en masse, often marking the bottom of a downtrend rather than the start of a new one.
Put simply, stocks don't usually move lower when there's no one left to sell. The factors in play suggest this drop marks the end of PLAY's decline, not the beginning of a fresh down leg.
Overlooked Company Targets Oil Rigs Pipelines and Tanker Ships (Ad)
A small company has developed water-based cleaning technologies aimed at some of heavy industry's toughest problems, from paraffin-clogged pipelines to hardened fuel inside tanker ships.
In a recent test, its marine formulation dissolved solidified heavy fuel oil almost instantly, tackling one of the toughest substances to remove.
The company targets oil and gas, shipping and environmental remediation, each a multibillion-dollar industry, and is now moving from testing toward commercial adoption.
See why this overlooked company may be nearing a critical inflection point
Back-to-Basics Strategy Progresses
While consumer headwinds affect traffic and costs continue to rise, the company is leaning hard into its Back-to-Basics strategy, and it is paying off. Remodeled and new stores significantly outperform the old, with improvements across business channels. The takeaway is that headwinds will impair results but will not last forever, and the stage is set for an accelerated recovery when consumer habits shift. Until then, the company’s efforts are producing positive free cash flow (FCF), primarily due to spending control, which is a universally good sign of business improvement.
The biggest risk is the debt load, but it appears to be contained as of Q2. Debt is high, impairing cash flow and limiting visibility, but improvements in FCF, the impact of sale-leaseback transactions, and available liquidity offset these pressures. Available liquidity is nearly $500 million and provides a decent cushion for near- to mid-term operations.
Weak Results Trigger Market Reset for PLAY Stock
Dave & Buster’s did not have a good quarter, despite the signs of structural improvement. Sales fell by 2.4% to $544.1 million, 230 bps worse than expected. The decline was driven by negative comp store growth of about 2.9%, offset by a higher store count. Store count grew 5.5%, increasing store operating weeks by 4.5%, but gains were undermined by a 6.3% decrease in weekly revenue per square foot.
Looking ahead, a return to comp growth is the trigger for buying and may occur over the next few quarters. Highlights from the release include commentary indicating sequential monthly comp improvement at quarter-end and a trend extending into early Q3. Management, however, has backed off on an explicit timeline, choosing a “laser focus” on new store openings instead until comps turn decisively positive.
Earnings were a mixed bag. Headline GAAP and adjusted earnings per share (EPS) were weaker than expected, including a $12.5 million net loss and lower EBITDA. The good news is positive free cash flow and the ability to continue executing the strategy. That includes permanently lifting former CFO Darin Harper to CEO. He has intimate knowledge of the operations, having been Main Event's CFO prior to its acquisition and central to developing the Back-to-Basics strategy.
Is This the New Normal for Gold? (Ad)
Barrick Mining has spent decades building one of the world's great gold districts in Nevada, anchored by Fourmile, Goldrush, and Cortez Hills, a region that could hold as much as 60 million ounces of gold.
Bordering Fourmile and less than a mile from Goldrush sits a little-known explorer now moving from historical data toward active exploration, setting targets and preparing for a maiden drilling program.
With gold trading near record highs, this could be a pivotal stage for an overlooked name in the district.
See why this overlooked gold explorer could be entering its most important stage
Short Sellers Drive PLAY to Fresh Lows While Analysts See Deep Value
Short sellers are part and parcel of this stock price decline. Short interest was down from its summer peaks as of early September, but still aggressively high at over 25%. With this in play, the stock had little choice but to move lower amid bearish catalysts, and it did.
The caveat is that analysts and institutions continue to reflect confidence in the long-term outlook. Nine analysts tracked by MarketBeat peg the stock as a consensus Hold, with coverage and sentiment steady over the trailing 12 months and a deep value indicated by the price targets.
The consensus target suggested more than 135% upside from the post-release open, but it is the range of price targets, specifically the low end, that matters. PLAY’s post-release stock price plunge took it not only below critical support but also nearly 40% below the low-end price target, to irresistible value levels. The question now is whether the shorts will start covering soon or wait until subsequent reports, when better results may be revealed.
The market got the report wrong by focusing on headline losses and consumer weakness while missing the structural improvement. The quarter-end shift to comp improvement and positive free cash flow are tailwinds to carry the business into Q3, which is traditionally the weakest. A strong Q3, followed by a stronger Q4 and subsequent Q1, traditionally the strongest period of the year, will go a long way towards restoring investor confidence. As it stands, the forecast for holiday retail spending is a year-over-year acceleration to nearly 5%, suggesting strength in other consumer segments.
Among the risks for Dave & Buster’s is consumer strain. Higher energy costs and overall inflation pinch consumer wallets, especially among lower-income households, potentially limiting discretionary purchases. The latest income and spending data revealed inflation rising faster than wages, a clear sign that consumers are feeling the pressure.
Recommended Stories
- Running on Empty: 3 Energy Plays for Europe's Deep Freeze
- Get this “Fed ticker” before September 16 (From Brownstone Research)
- 3 Healthcare Stocks for 3 Stages of Life
- The Rumors About Elon’s Next Move Are Spreading Fast (From The Oxford Club)
- Curaleaf Tries To Roll Up Aurora In a Hostile Cannabis Bid
- MarketBeat's Most Downgraded Stocks in Q3: 2 Look Cheap, 1 Looks Risky
- Cashing in on the Qubit: NVIDIA Takes the Quantum Leap
Stay Ahead of the Market
The best investment opportunities don't wait. Get our research and stock ideas delivered straight to your smartphone—so you never miss a market-moving opportunity. Our text alerts ensure you see timely stock ideas and professional research reports instantly, whether you're in a meeting, commuting, or away from your desk.


