I have publicly predicted six major American crashes, before each one happened. (From Weiss Ratings)
Key Points
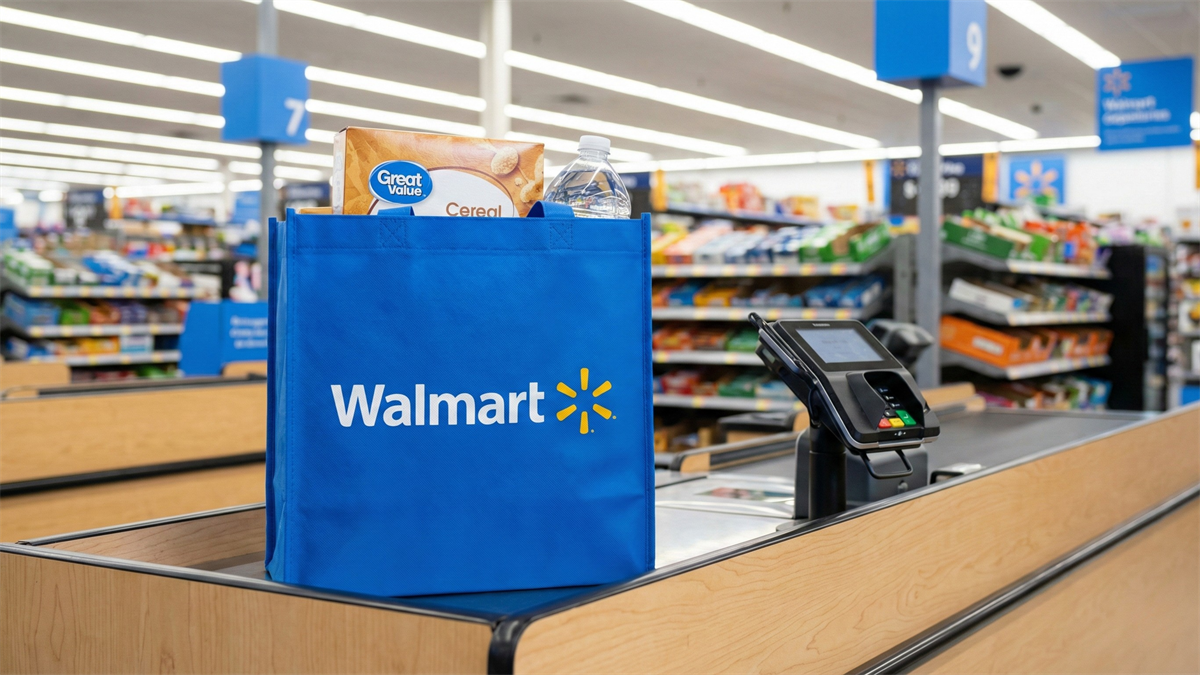
- Store brands now account for a record 23.8% of units sold, as national brand volumes fell while store brand volumes rose slightly.
- McCormick's quarterly earnings beat estimates, but shares fell because organic growth relied on price increases while consumer volume declined.
- Kroger and Walmart are expanding private-label lines like Private Selection and bettergoods to capture margin as shoppers shift away from national brands.
- Special Report: A Wall Street Veteran's Weekly Options Strategy Explained (From Base Camp Trading)
Store brand sales are growing as consumers look for ways to mitigate elevated food prices. Private label sales in the United States reached $330 billion in 2025, according to Circana. That shift has continued in 2026.
But there's a larger fight over shelf space that is reshaping packaged food stocks. On the surface, national brands still look healthy. Their dollar sales grew 2.2% in the first half of 2026. Store brand dollar sales were flat.
That sounds like the name brands are winning. They aren't.
Look at units instead. Store brand unit sales rose 0.2% over the same stretch. National brand units fell 0.5%. Store brands now account for a record 23.8% of all units sold.
In other words, the major labels are growing revenue by charging more, not by selling more. But that pricing power isn't attracting value-seeking shoppers who are voting with their dollars.
For investors, it comes down to which side of the trade you want to own. In the just-finished earnings season, one retailer was a clear example of the dominance of private labels. Two other retailers are taking the "if you can't beat them, join them" approach.
Forbes calls this a "golden era" for retirement income (Ad)
Forbes recently called a new category of exchange-traded income funds a 'golden era,' and Bloomberg noted the eye-popping yields are fueling a boom among everyday investors. Three years ago, barely a dozen of these funds existed - today there are more than 100, holding over $140 billion.
These funds trade on the NYSE and NASDAQ and are built to generate monthly income. Some investors are targeting $5,000 a month with roughly one-tenth of the nest egg Wall Street says you need.
Watch the short briefing to see how this income approach works
McCormick Beat Estimates—But the Stock Still Fell
McCormick (NYSE: MKC) reported fiscal third-quarter results on Oct. 1. On paper, it was a strong quarter. Net sales jumped 17.4% to $2.02 billion. Adjusted earnings per share (EPS) of 86 cents topped estimates of 76 cents, and gross margin expanded 190 basis points.
The detail underneath tells a different story. Most of the sales jump came from the McCormick de Mexico acquisition. Organic growth was just 1.9%. Pricing added 2.2%, while volume and mix subtracted 0.3%. In the Consumer segment, volume and mix of the company's name-brand spices and seasonings fell 1.1%.
Shares slid on the morning of the report. Though they have recovered since then, the initial selling reaction makes sense.
Wall Street isn't grading McCormick on one quarter's margin. It's grading whether its pricing power will last. That means volume (i.e., units) is the scorecard.
Price Hikes Have a Shelf Life
For three years, packaged food companies operated from a similar playbook. Costs rose, so prices rose. Volumes dipped, but margins held. Investors mostly rewarded the companies with the most pricing power.
That tolerance is fading. Store brands typically sell for about 20% less than national labels. Most shoppers now say the quality is similar or sometimes even better.
Once a shopper switches and isn't disappointed, the habit tends to stick. That's what makes private label gains so hard to reverse. Each price increase on a brand name gives customers a reason to try the alternative.
The industry is split into two camps. Some brands are cutting prices to win shoppers back. Others keep raising them to cover costs. Investors should know which camp their holdings fall into, because the outcomes will diverge.
Your Free Report (Inside) (Ad)
A free copy of Options Trading Made Simple is available now but wont stay that way for long.
Chris Rowe calls it The 10-Minute Guide to Start Trading Options Today, built to help you open your first options trade with less capital than buying shares outright.
Download your free copy of Options Trading Made Simple before it's gone
2 Retailers Are Playing a Different Game
Kroger (NYSE: KR) and Walmart (NASDAQ: WMT) see this shift from the other side of the transaction. To them, store brands are an engine for margin growth.
Kroger's Our Brands outpaced national brands by 175 basis points in fiscal Q1. In Q2, private-label penetration rose by about half a percentage point. Private Selection sales jumped more than 14%, led by ready-to-eat meals.
That doesn't make Kroger a clear winner. Its Q2 gross margin slipped to 22.7% on pharmacy and freight headwinds. But its private label business is one of the few levers working in its favor.
Walmart is pushing upmarket too. Its bettergoods line, launched in 2024, was its biggest private food brand debut in two decades.
It targets shoppers who want better value than the company's Great Value brand without paying name-brand prices.
The economics are simple. Retailers control the cost, the shelf placement, and the margin.
Every unit that moves from a national brand to a store brand improves their mix.
What Investors Should Watch Now
The perception is that packaged food is a safe, defensive corner of the market. The fundamentals say that defense now has a cost.
Three signals matter most:
Unit volume, not just organic sales. Organic growth built only on price is borrowed time.
Promotional spending. When brands discount to win shoppers back, margin gains usually reverse.
Retailer commentary on private label penetration. It's the clearest real-time read on where shoppers are heading.
For McCormick, next quarter's consumer volume is the number that matters. Management expects volume to improve in Q4. The pending Unilever Foods combination adds another layer to the story.
The grocery store shelf isn't getting any bigger, so someone has to give up space. Right now, the data says it's the name brands. Investors should position themselves accordingly.
Further Reading
- 3 Stocks Chopped in Half: Why These Drops May Be Structural, Not a Dip
- Do NOT Buy SpaceX – Do This Instead (From Stansberry Research)
- Home Depot and Lowe’s Hit 52-Week Lows—But Analysts Aren’t Giving Up
- Ian Cooper Unveils a Simple Options Trade Strategy (From TradeWins)
- Utilities Are Bouncing Back—These 2 Giants Could Signal the Next Big Sector Rally
- Q3 Earnings Could Blow Past Consensus—Be Ready for What Comes Next
- Why Wall Street Expects Even More From SanDisk After Its 575% Rally
Stay Ahead of the Market
The best investment opportunities don't wait. Get our research and stock ideas delivered straight to your smartphone—so you never miss a market-moving opportunity. Our text alerts ensure you see timely stock ideas and professional research reports instantly, whether you're in a meeting, commuting, or away from your desk.


