Get this “Fed ticker” before September 16 (From Brownstone Research)
Key Points
- Braze shares fell after a slightly soft Q3 earnings guidance, but analysts have raised price targets and maintained a consensus Moderate Buy rating with 95% buy-side bias.
- Braze posted strong Q2 results, including 26.2% revenue growth, record free cash flow, and adjusted earnings per share that beat expectations by more than 1,850 basis points.
- Dilution from share-based compensation remains the biggest risk for shareholders, though growth catalysts like Braze AI products and an expanding AWS partnership support the bullish case.
- Special Report: Small Colorado Company (Backed by Sam Altman) Could Save U.S. Power Grid (From Altimetry)
Braze’s (NASDAQ: BRZE) September price crash looks like a buying opportunity, because the trigger for selling was questionable, and analyst activity has run counter to the move. The trigger was softer-than-expected Q3 guidance that forecast a penny less in earnings than the consensus, an arguably bearish detail, but one offset by many positives.
The positives include business traction, accelerating penetration, and a full-year outlook that was not only above forecasts but likely cautious.
What did the market get wrong? Braze is not a legacy consumer platform but an emerging, mission-critical software layer that streams real-time consumer data and enables real-time responses to consumer habits.
The analyst responses to the company's Q2 earnings news should say it all. The news triggered numerous revisions, all of which included increases to price targets or reaffirmed targets aligned with the trend. The trend is increasing coverage, firming sentiment, and rising price targets, with the consensus up by more than 1,000 basis points on the fresh action alone. Consensus forecasted 25% upside relative to the pre-release close, and that upside only increased with the post-release selling. MarketBeat tracks 21 analysts, pegging the stock as a consensus Moderate Buy, with a 95% Buy-side bias within the data.
Here’s Why Trump Won’t End The Iran War (Ad)
Trump has called an Iran deal close 38 times since the war began, yet the fighting keeps flaring back up.
One day it's a ceasefire, the next it's bombs again. The back and forth may be masking a bigger story most investors are missing.
See the real reason this conflict may never fully end.
Uncover the real reason Trump may never end this war
Braze Is Blazing Hot in Q2, Raises Guidance for the Year
Braze had a smoking hot Q2 with revenue growing by 26.2% to $227.2 million, a year–over-year acceleration that outpaced the consensus estimate by over 300 basis points. New clients, upsells, and renewals drove strength. Subscriptions, the core business, grew 20.9%, with Professional more than doubling. The net retention rate (NRR), a measure of penetration gains, came in at 110% year-over-year (YOY), up 200 basis points, showing increasing momentum. Customers grew by 15%, led by a 28% increase in larger clients contributing at least $500,000 in annual recurring revenue (ARR).
The company experienced margin pressures and continues to post GAAP losses, but offsets them with operational quality and revenue leverage. The net result in Q2 was record operating and free cash flow. Free cash flow was up more than 6x YOY, and the 19 cents in adjusted earnings per share was up 26% YOY despite dilution. The key point is that Q2 adjusted earnings per share (EPS) came in more than 1,850 bps above expectations, pointing to strength in upcoming quarters and a potential for cautious Q3 guidance.
Guidance was the sticking point in the release, but only marginally. While the Q3 adjusted EPS forecast fell short of consensus by a penny, it is likely cautious, given Q2 strength and signs of momentum both internally and across the SaaS industry. Either way, this single weakness is offset by a better-than-expected Q3 revenue forecast and full-year guide. The full-year guidance expects revenue to top $910 at the low end, well above consensus, with similar earnings performance.
Dilution Is the Biggest Risk for Braze Shareholders in 2026
SaaS-Pocalypse fears aside, the biggest risk Braze shareholders face this year is dilution. While the company is profitable and cash-flow positive, share-based compensation offsets that and drives quarterly dilution. Dilution is not expected to end soon, but adjusted profitability is forecast to improve, setting the stage for inflection within the next year or two.
Braze’s balance sheet suggests it can sustain operations while investing in growth. Q2 highlights included increased cash, steady assets, and moderate increases in liabilities, leaving equity down marginally but still in solid shape with low leverage and net equity.
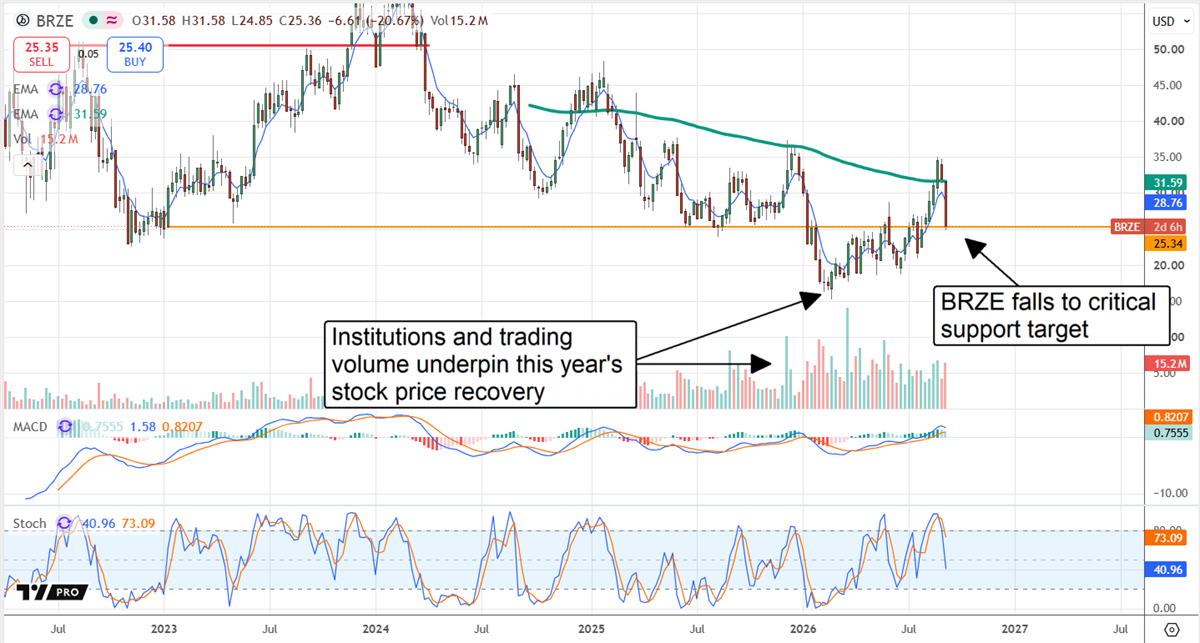
Institutions are likely buyers on this dip. The group owns more than 90% of the shares and has been accumulating in 2026, aligning with a stock price bottom. The narrative in early September is that the post-release pullback put the market back into the “Buy Zone," likely to trigger another surge in accumulation. The key support levels and target regions for entry signals are near $25 and $16.
Why the Richest Man Alive Lives in a $50,000 Shack (Ad)
Elon Musk is worth more than anyone in history, yet he lives in a 400-square-foot prefab home in Boca Chica, Texas. Every payday he's earned, from $22 million at Zip2 to $175 million at PayPal, has gone straight into his next venture.
Now a $2.1 trillion SpaceX IPO has fueled his next move. Former CIA analyst Dr. Mark Skousen says he's identified three companies Musk is targeting next.
See Musk's three target companies before he makes his move
Braze AI Drives Adoption and Retention
This year’s catalysts include the rollout of Braze AI products, which are driving client wins and penetration. Products such as Braze AI Operator, Agent Console, and Decisioning Studio enable automation of personalized workflows. The utility is reflected in client wins, including a growing number of large enterprises providing upwards of $500,000 in ARR and visibility into long-term cash flow.
Another catalyst is an expanding collaboration with Amazon’s (NASDAQ: AMZN) AWS, as well as other hyperscale data companies. The collaboration embeds Braze products alongside AWS offerings, creating expanded co-sell and upsell opportunities, along with increased go-to-market and consumer incentives to drive adoption. Braze’s clients can leverage AWS’s deep machine-learning and data-mining capabilities to enhance experiences and consumer outcomes.
Featured Articles
- Why Bitcoin ETFs May Be Worth Another Look as Inflows Rebound
- The $15 Gold Fund That Pays Up to $1,152/Month (From Investors Alley)
- 3 Small-Cap Biotechs With Binary Catalysts on the Calendar
- The REAL Reason Trump is Invading Iran (From Banyan Hill Publishing)
- Planet Labs Has Fallen Back to Earth, But Wall Street Still Sees a Rebound
- As Homeowners' Premiums Surge, This Insurer Is Posting Record Profits
- Nasdaq’s $100 Million Kraken Bet Prepares It for a Market That Never Closes
Stay Ahead of the Market
The best investment opportunities don't wait. Get our research and stock ideas delivered straight to your smartphone—so you never miss a market-moving opportunity. Our text alerts ensure you see timely stock ideas and professional research reports instantly, whether you're in a meeting, commuting, or away from your desk.


