Gold did this exact thing in 1975… [then exploded] (From Golden Portfolio)
Key Points
- Guidewire shares fell after the company issued cautious guidance tied to its shift from legacy licensing to cloud-based subscription revenue.
- Despite the guidance-driven selloff, Guidewire posted 15% revenue growth, expanding margins, and 51.4% year-over-year operating income growth last quarter.
- Analysts remained bullish overall, with no downgrades, a consensus price target near $220, and continued institutional buying supporting a potential rebound.
- Special Report: A $382 trillion migration and the position no one is talking about (From Awesomely)
Guidewire Software’s (NYSE: GWRE) post-release stock plunge looks like a knee-jerk reaction that will soon correct.
The plunge was caused by tepid guidance linked to a strategic shift from legacy licensing models to cloud-based subscription models, which provide lower revenue but better margins. The downside is tepid topline growth, but what is sluggish growth in the face of wider margins other than an opportunity to improve both?
As it stands, the cloud transition underpins a robust outlook, and its near-term drag on revenue is widely seen as fading. The more critical story is what that transition is now producing: accelerating recurring-revenue growth and improving profitability.
While adjusted net income grew only 300 basis points faster than revenue, it was impacted by increased investment, and operating income grew more substantially. Up 51.4% year over year (YOY), operating income points to ample cash flow and capital-return capacity over time.
The 38% Crash Warning Every Retirement Saver Needs to Read Right Now (Ad)
The AI trade has pushed stocks to record highs, everyone feels good, and retirement accounts look great on paper—that's exactly what makes this moment dangerous. Citigroup Research recently modeled a 38% S&P 500 decline by 2027, not because AI fails, but because it works: as automation rises, white-collar wages weaken, spending slows, and the entire debt-fueled structure holding markets up starts to crack. Your retirement account doesn't need a crash to lose ground—volatility plus rising costs erode savings quietly, and by the time it shows up in your statement, it's already done the damage.
Learn how to add gold to your IRA tax and penalty-free
Guidewire Outperforms, Issues Cautious Guidance
Guidewire had a solid quarter despite the impacts of its strategy shift. Revenue grew by 15%, outperforming by 200 basis points (bps), driven by a 32% increase in subscriptions and a 10% increase in services. Licensing, the legacy business, contracted 18% and is expected to continue declining in the upcoming quarters. Cloud annual recurring revenue (ARR), the measure of annual subscription-based sales, grew 35% to 84% of total ARR, providing visibility into future results. It suggests the cloud-based revenue growth will accelerate.
Margins were the sweet spot, up in all comparisons, leaving adjusted earnings at 99 cents, up 22% YOY and a nickel ahead of consensus. The only downside was the impact of capital expenditures (CapEx) and investments, which reduced bottom-line strength.
Cash flow is sufficient to sustain the fortress-like balance sheet while returning capital. Capital returns include aggressive share buybacks, which reduced the share count by 3% YOY as of fiscal Q4, and are expected to continue in future quarters.
The headwind today is that Q1 forecasts were below expectations, but a catalyst for share price recovery is already in play. Guidance is likely to be cautious, given the company’s cloud strengths and cues from other AI-enabled cloud-based software providers, collectively reflecting accelerating demand across the software ecosystem. In this scenario, the company could outperform in the next quarter, causing already-strong full-year guidance to be revised upward.
Analysts Respond With Caution, Outlook Remains Bullish
The primary takeaway from analysts' responses to the release was caution centered on the tepid revenue outlook. No downgrades were issued, but numerous price targets were reduced, limiting the upside potential but reinforcing the consensus. Consensus, as reported by MarketBeat, is pegged in the low $220s, indicating a 10% upside relative to the pre-release close and closer to 35% following the release. GWRE stock is likely to remain under pressure over the coming months, without a significant catalyst for a rebound until the Q1 results are released.
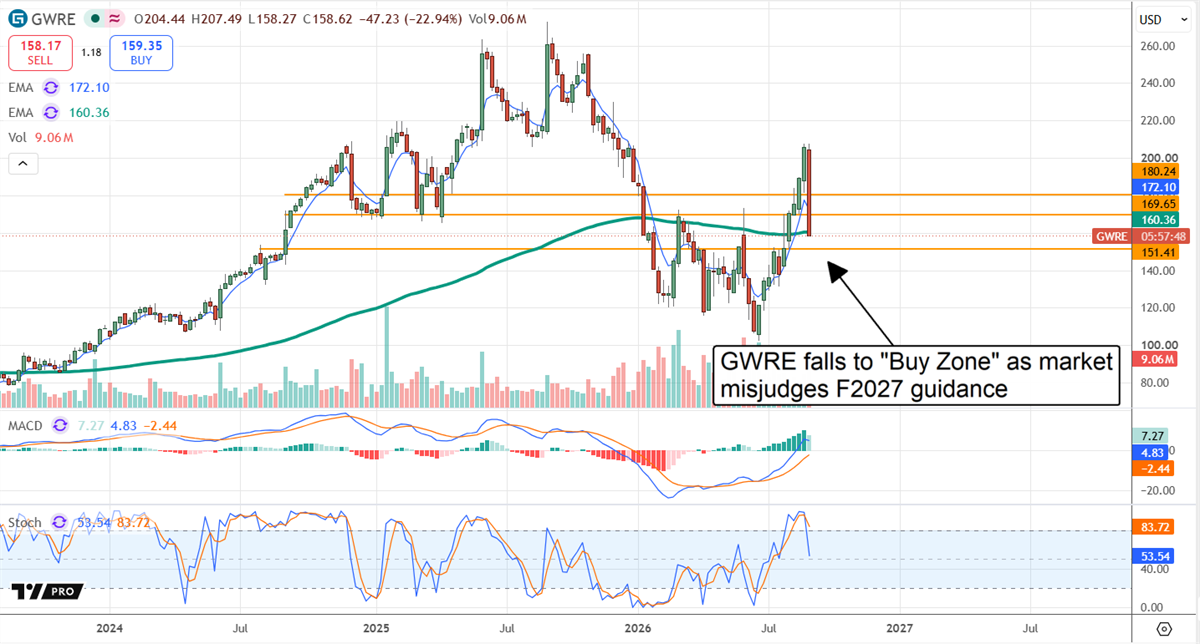
Technically, GWRE stock is in the midst of a major reversal, and the post-release plunge aligns with that trend. Price action moved to fresh long-term highs earlier this year, breaking above several resistance targets, including a cluster of moving averages that now form a Golden Cross. As of early September, the story is that GWRE’s market has retreated to the pivot point to retest support, and it is likely to hold.
Institutional activity was bullish ahead of the release and is likely to remain so afterward. Although selling capped gains earlier in the year, the group reverted to an accumulative posture in early Q3, helping drive the stock price through its resistance targets. The likely outcome is that this group buys the dip, potentially accelerating accumulation because of the steep discount.
The $15 Gold Fund That Pays Up to $1,152/Month (Ad)
Gold is hitting record highs, but most investors are leaving income on the table. A $15 fund is quietly paying out up to $1,152 a month to regular investors - no mining stocks, no options, no physical metal required.
Chief Income Strategist Tim Plaehn calls it a breakthrough strategy that transforms gold's rally into reliable monthly payouts. The next distribution is just days away.
Discover the gold income fund before the next payout date
High-Valuation Versus Deep Moat and Visibility
Guidewire’s biggest risk is its valuation. The stock traded at about 50x earnings ahead of the report, setting the stage for execution-related stock price volatility, which the weak guidance triggered. Investors are getting it wrong, however. Near-term headwinds are easing, and the long-term outlook includes improving margins, cash flow, and capital return, driven by the company's ever-deepening moat.
Guidewire is a mission-critical software layer for insurance companies globally, providing the operating systems for over 500 insurers and counting. It is indispensable to their operations and incredibly costly to change, as it affects 100% of their business. A clear sign of strength is the nearly 100% retention rate, signaling that once onboarded, an insurer is a customer for life. Within that, the company has an unseen growth driver tied to insurance inflation; Guidewire's network earns a toll as inflation costs increase and natural disasters drive activity.
Featured Stories
- Rocket Lab Tackles a Supply Chain Bottleneck as the Stock Hunts for a Bottom. Time to Buy?
- The Rumors About Elon’s Next Move Are Spreading Fast (From The Oxford Club)
- Optical Cable Corporation Is Starting to Get the Market’s Attention
- This 15 Dollar Gold Fund Pays Investors Every Friday (From Investors Alley)
- Oil Above $100 Is Creating a New Opportunity Beyond the Major Producers
- Is Nike's Index Demotion a Warning or a Buying Opportunity?
- American Eagle Goes on Sale: Is It Time to Buy?
Stay Ahead of the Market
The best investment opportunities don't wait. Get our research and stock ideas delivered straight to your smartphone—so you never miss a market-moving opportunity. Our text alerts ensure you see timely stock ideas and professional research reports instantly, whether you're in a meeting, commuting, or away from your desk.


