Get this “Fed ticker” before September 16 (From Brownstone Research)
Key Points
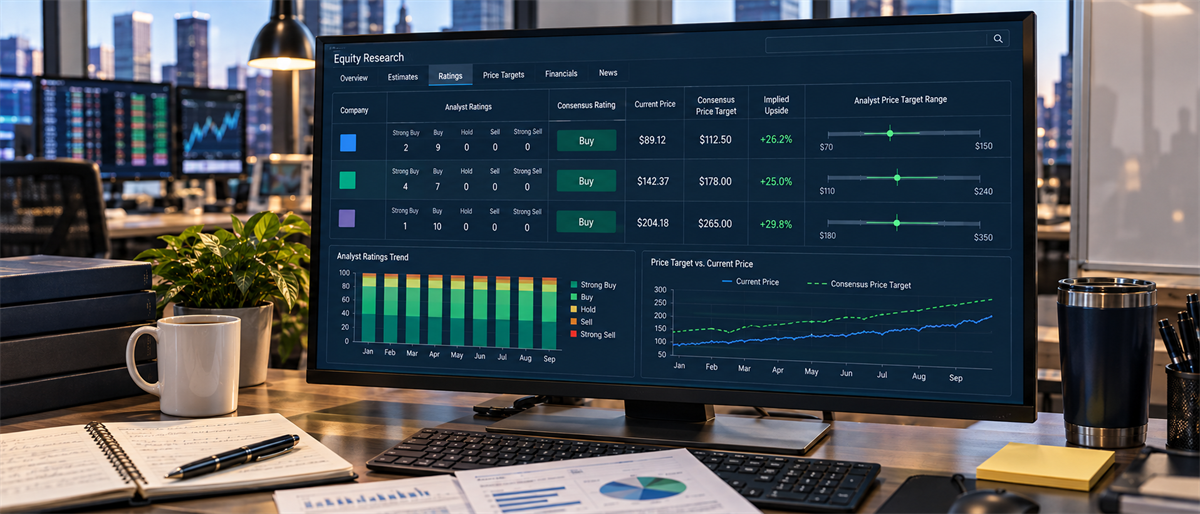
- Nasdaq, Arista Networks, and Mastercard each hold an outright Buy consensus with double-digit implied upside despite very different business models and performance trends.
- Nasdaq offers the widest upside potential at roughly 24% despite an 8% stock decline this year, supported by its growing Verafin data and crime-detection business.
- Arista Networks has surged more than 47% in 2025 on AI networking demand, while Mastercard's steady compounding and strong earnings make it an attractive entry point.
- Special Report: Small Colorado Company (Backed by Sam Altman) Could Save U.S. Power Grid (From Altimetry)
Price targets aren't promises or certainties, but when a group of Wall Street analysts assigns a stock a Buy rating with meaningful upside to their consensus target, it is worth paying attention to what they see. The three names below all share that profile. Each has an outright Buy consensus, sits high on MarketBeat's top-rated stocks list, and offers double-digit implied upside from where it trades today. What makes the trio interesting is how different they are from one another, spanning financial exchanges, AI networking, and global payments, yet all landing in the same favorable spot with the analyst community.
Is This the New Normal for Gold? (Ad)
Barrick Mining has spent decades building one of the world's great gold districts in Nevada, anchored by Fourmile, Goldrush, and Cortez Hills, a region that could hold as much as 60 million ounces of gold.
Bordering Fourmile and less than a mile from Goldrush sits a little-known explorer now moving from historical data toward active exploration, setting targets and preparing for a maiden drilling program.
With gold trading near record highs, this could be a pivotal stage for an overlooked name in the district.
See why this overlooked gold explorer could be entering its most important stage
Nasdaq: A Laggard the Street Still Believes In
Nasdaq (NASDAQ: NDAQ) is best known for the exchange that bears its name, but the modern company is far more than just a trading venue. The company has built a growing business in market data, indexing, and anti-financial-crime technology through its Verafin division, giving it recurring, software-like revenue streams alongside its traditional listings and trading operations.
The stock has struggled this year, though, down about 8%, which makes the analyst optimism particularly notable. Nasdaq holds a Buy consensus from 11 analysts, and the average price target of $110.30 implies close to 24% upside from current levels, the highest of this group.
It ranks in the 99th percentile of MarketBeat's finance-sector rankings, pays a strong and growing dividend, and expanded its Verafin crime-detection partnership recently to cover both cash and crypto transactions.
From a technical point of view, the stock is still in a higher timeframe uptrend, although more recent price action has been in line with the overall market, range-bound and choppy. The stock is stuck in a broad range, with $76 acting as support and $100 acting as the all-important level that would need to be cleared for upward momentum to take charge.
Arista Networks: The Momentum Name of the Group
Arista Networks (NYSE: ANET) sits at the opposite end of the performance spectrum. The company builds high-performance Ethernet switches and networking software that tie together the massive data centers powering artificial intelligence, and demand has been surging. As AI clusters scale to hundreds of thousands of accelerators, the networking layer that enables those chips to communicate has become mission-critical, and Arista is one of its clear leaders.
That positioning has driven the stock up more than 47% this year, by far the best performer of the three. Even after that run, the analyst community sees room to run, with a Buy consensus from 23 analysts and an average price target of $227.80 implying roughly 15% additional upside.
The fundamentals underpinning the move are genuinely impressive, with net margins near 38% and projected earnings growth above 23%. The potential red flag, though, is valuation: Arista trades at more than 50 times forward earnings, a premium that demands stellar execution. But for a business this profitable riding a structural tailwind this strong, the Street clearly believes the growth justifies the price.
A US Gold Explorer Approaches a Key Drilling Milestone (Ad)
A little-known Arizona gold explorer just hit 66.2 metres grading 6.57 g/t gold, including 20.7 metres at 18.25 g/t.
After roughly 21,000 metres of drilling, the company is closing in on its first-ever mineral resource estimate, expected in Q3 or Q4 2026.
That estimate could offer the market its first real look at the scale of this emerging gold system.
See what could be next for this US gold explorer
Mastercard: A Quality Compounder on Sale
Mastercard (NYSE: MA) is one of the highest-quality businesses in the entire financial sector, yet its stock has gone essentially nowhere this year.
That stall is what makes it interesting. The global payments network runs a near-unassailable business model, taking a small cut of an enormous and growing volume of electronic transactions worldwide, and it does so with awesome profitability.
The company posted Q2 2026 earnings on July 30, beating the consensus estimate by 27 cents, with quarterly revenue up more than 14% year over year to $9.28 billion.
MA has a Buy consensus from 31 analysts, the deepest coverage in the group, and an average price target of $666.64, pointing to about 17% upside. With a low beta of 0.74, it also offers a relatively smoother ride than most, a rare combination of defensive stability and durable growth. After a year of treading water while earnings kept climbing, the valuation has quietly become more reasonable, and analysts appear to view the current level as an attractive entry into a proven compounder.
The Common Thread
These are three very different businesses with one shared conclusion from Wall Street. Each has room to run. Nasdaq offers the widest implied upside, Arista brings the strongest momentum and growth, and Mastercard provides the steadiest quality at a reasonable price.
Of course, analyst targets are only one input, and none of these names is without risk. That's clearly seen in Arista's premium valuation and Nasdaq's recent underperformance. However, when a stock combines an outright Buy rating with double-digit upside potential, it at the very least justifies a closer look.
Featured Stories
- Enterprise AI to Boost Broadcom's Software Business? What Industry Data Shows
- Trump goes "all-in" on Grand Canyon energy breakthrough (From Behind the Markets)
- IonQ and NVIDIA Just Cracked a Major Quantum Computing Bottleneck
- Here’s the stock symbol I’ve promised (From Stansberry Research)
- This Gold ETF Turns a Non-Yielding Asset Into Monthly Income—But There’s a Catch
- 3 Luxury Consumer Brands to Watch in a Beaten-Down Sector
- Jackson’s Record Quarter Powers the Bull Case
Stay Ahead of the Market
The best investment opportunities don't wait. Get our research and stock ideas delivered straight to your smartphone—so you never miss a market-moving opportunity. Our text alerts ensure you see timely stock ideas and professional research reports instantly, whether you're in a meeting, commuting, or away from your desk.


